Retiring in South Africa: Cost of Living and Where to Settle
There comes a stage in life when the question of where to live is no longer dictated by an office, a commute, or the demands of a career.
For those fortunate enough to choose, retirement offers something increasingly precious: freedom.
And for thousands of foreign nationals who have fallen in love with South Africa—some during a holiday, others after returning year after year—the prospect of making the country their home is enticing.
The attraction is easy to understand.
Few countries can offer the extraordinary contrasts of South Africa. Cape Town sits between mountain and ocean; the Cape Winelands unfold barely an hour away; the Garden Route offers forests, beaches and quieter coastal living; while further north, the Lowveld places some of Africa’s greatest wilderness areas within reach.
Add to this a favourable climate, sophisticated private healthcare, established financial services and, for many foreign retirees, an attractive cost of living, and South Africa begins to look like considerably more than a holiday destination.
South African law does provide for exactly this: a visa built for people who want to spend their retirement here rather than work through it. The requirements, the costs and the changes government has proposed are set out in full on our South African retirement visa page. What follows here is everything else — what it actually costs to live in South Africa, where retirees end up settling, how healthcare works, and the point at which SARS starts taking an interest in you.
What it actually costs to live here
We have deliberately not opened this section with a single monthly figure. Every site that does is quoting the same crowd-sourced data, it is usually a year out of date, and the rand moves enough that a number written in March is misleading by September. What is more useful is knowing which way each cost cuts.
Cheap, by the standards of most countries retirees arrive from: property, whether buying or renting. Domestic help and garden services. Fresh food, wine and eating out. Rates and water. Labour of almost every kind — a plumber, a painter, someone to service the car.
Not cheap, and occasionally a shock: anything imported, which covers cars, electronics, appliances and most branded goods. Electricity, which has risen far faster than inflation for well over a decade. Private medical cover, dealt with below, which is usually the largest single line in a retired household’s budget. Insurance. Private schooling, if grandchildren end up in the picture.
The visa threshold makes a reasonable yardstick. R37,000 a month is a comfortable income across most of the country — noticeably comfortable in the Garden Route, the Overberg or a Karoo town. On Cape Town’s Atlantic Seaboard, or in the more sought-after southern suburbs, it is closer to adequate than generous. The same income buys markedly different lives depending on where you point it, and that spread is wider here than in most of Europe.
One line people routinely forget: a car. Public transport is not a realistic substitute outside a handful of corridors, so nearly every retired household runs at least one vehicle — and second-hand prices are high by international standards.
Where retirees actually settle
Almost everyone arrives thinking Cape Town. A good number stay; a good number discover that what they wanted was the coast, the weather and a slower week, none of which require living in the city.
- The Cape Peninsula — the southern suburbs, Simon’s Town, Kalk Bay. Everything within reach, the country’s best private hospitals, and the highest prices.
- The Helderberg — Somerset West and Gordon’s Bay. Cape Town’s amenities forty minutes away, at a meaningfully lower cost. The largest concentration of retirement estates in the country.
- The Overberg — Hermanus, Stanford, Greyton. Coastal or village life, whale season on the doorstep, a settled community of retirees.
- The Garden Route — Knysna, Plettenberg Bay, Sedgefield, Wilderness. Forest and lagoon, mild all year, quiet outside December when it emphatically is not.
- The Eastern Cape coast — St Francis Bay, Kenton-on-Sea, Port Alfred. The best value on the coast, at the cost of distance from a major hospital.
- The KwaZulu-Natal north coast — Ballito, Salt Rock, Umhlanga. Warm sea, subtropical, and the only option on this list where you can swim comfortably in July.
- Inland villages — Prince Albert, McGregor, Clarens. Cheapest of all, and the right answer for some people and quite the wrong one for others.
One local feature worth understanding before you commit. Many South African retirement estates sell life rights rather than ownership. You buy the right to occupy the unit for the rest of your life; on death it reverts to the developer and your estate receives an agreed amount back. It is cheaper to get into than sectional title, and it removes levies and maintenance headaches, but there is no capital growth and what your heirs receive is fixed by the contract. Neither model is better — they answer different questions — but foreign buyers regularly sign a life rights agreement believing they have bought a property.
Worth saying plainly while we are on the subject: buying property here, on any model, does not give you the right to live here. Ownership and immigration status are entirely separate questions in South African law.
The single most useful thing we tell clients: rent for six to twelve months before you buy anything. Winter in Knysna is a different proposition from a January holiday there, and the cost of discovering that after transfer is considerable.
Healthcare, and the trap nobody warns you about
South Africa’s private healthcare is genuinely good. The hospitals are modern, the specialists are well-trained, waiting times are short, and treatment costs a fraction of what it would cost in the United States. The public system carries most of the population and is under real strain, which is why essentially every retiree here carries private cover.
Here is the part that catches people. Medical schemes may apply a late-joiner penalty to anyone who joins at age 35 or older without a history of South African medical scheme membership. The penalty is a permanent loading on your monthly contribution — it does not fall away — and it runs from 5% to 75% depending on how many years you were without cover. A foreign national joining a scheme for the first time at 60 is, by definition, at the wrong end of that range.
Waiting periods apply as well: typically 3 months for general conditions and up to 12 months for pre-existing conditions. Neither of these is a reason not to come. They are a reason to price medical cover properly before you commit to a budget, and to talk to a healthcare broker rather than assuming the first quote you see is the number.
On the National Health Insurance Act: it was signed into law but has not been implemented, and it faces constitutional challenges that were still before the courts through 2026. Medical schemes continue to operate exactly as they do now. Anyone telling you the position is settled is ahead of the facts.
Tax: when SARS starts taking an interest
Your visa and your tax position are separate questions with separate answers, and confusing them is expensive.
South Africa taxes residents on worldwide income and non-residents only on income from a South African source. You become a tax resident either by being ordinarily resident — broadly, this is the country you return to after your travels — or by the physical presence test, which requires 91 days in the current tax year, 91 days in each of the preceding five years, and 915 days in total across those five years. Failing any one of the three means you do not meet it.
The good news for most retirees is section 10(1)(gC)(ii) of the Income Tax Act, which exempts a pension or annuity received from a source outside South Africa as consideration for past employment outside South Africa. Where a working life was split between countries, the exemption is apportioned — the years of foreign service over total years of service. So a pension earned entirely abroad is generally exempt even once you are tax resident here, while one that includes South African service years is only partly so.
Double taxation agreements between South Africa and most Western countries address the overlap, and state pensions are often treated differently from occupational pensions. Estate duty is a separate matter again and worth planning for before you move assets here.
We are immigration consultants, not tax practitioners, and this is general information, not advice on your position. What we would say firmly is that this conversation belongs before the move rather than after — the physical presence test counts days you have already spent, and by the time it matters, the days are behind you.
More Than an Immigration Decision
There will always be paperwork.
Financial evidence must be prepared. Police clearances and supporting documentation must be obtained. Applications must satisfy the requirements of the Immigration Act and Regulations.
Those details matter enormously.
But they are not why people retire to South Africa.
People come because they have reached a point in life where they can choose differently.
They come for mornings beneath Table Mountain and evenings overlooking the Atlantic. They come for the Winelands, the bush, the beaches and the extraordinary amount of space this country still affords.
Some come because their children and grandchildren are here.
Others arrive knowing almost nobody and build an entirely new circle of friends.
And many discover that the country they once regarded as somewhere to visit gradually becomes somewhere they cannot imagine leaving.
And the visa itself
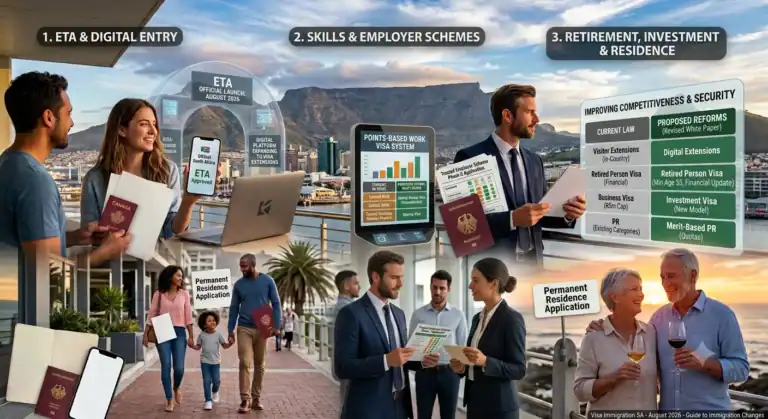
Everything above assumes you can be here lawfully in the first place. The route most people use is the retired person visa, which turns on a guaranteed monthly income rather than your age — and which the government has proposed changing. If your wealth sits in capital rather than in a pension, the financially independent permit may be the more direct route.
If you would rather start with a straight answer about your own circumstances, our visa eligibility assessment is free, and it will tell you if the answer is no.
Last reviewed 31 August 2026. General information about living in and moving to South Africa, not advice on your circumstances. Immigration requirements, medical scheme rules and tax thresholds change — confirm the current position and take tax advice from a registered tax practitioner before acting.